
The Supreme Court on September 28 refused to grant an interim stay on the Centre’s decision to introduce Merchant Discount Rate (MDR) on certain high-value UPI merchant transactions above ₹2,000. The court has sought responses from the Centre, the Reserve Bank of India and other concerned parties on a petition challenging the new framework.
The development has brought renewed attention to the future of UPI payments in India, which have become an important part of everyday transactions for consumers, retailers and businesses.
The petition before the Supreme Court challenges the framework announced by the government in September for specified person-to-merchant, or P2M, UPI transactions above ₹2,000. The court’s decision on Monday does not mean that the broader legal challenge has been decided. The matter will continue to be examined after responses are received from the concerned authorities.
What is changing for UPI payments?
The new framework does not introduce a charge on every UPI transaction. Person-to-person UPI transfers continue to remain outside the MDR framework. Merchant payments up to ₹2,000 are also excluded from the new charge.
For general P2M UPI transactions above ₹2,000, the MDR has been set at 0.4 per cent, with a maximum cap of ₹300 for transactions of ₹75,000 and above. Certain specified sectors, including railways, telecommunications, insurance, fuel and agricultural inputs, have a different flat MDR structure for transactions above the threshold.
MDR, or Merchant Discount Rate, is a fee associated with processing a merchant payment. It is distributed within the payments ecosystem among participating institutions and is different from a tax directly collected from consumers.
The framework also contains provisions intended to prevent the additional processing cost from being directly passed on to customers. Banks have been advised to ensure that merchants do not transfer the MDR to customers, while UPI app providers have been restricted from imposing platform fees or hidden charges on users under the framework.
Why the issue matters
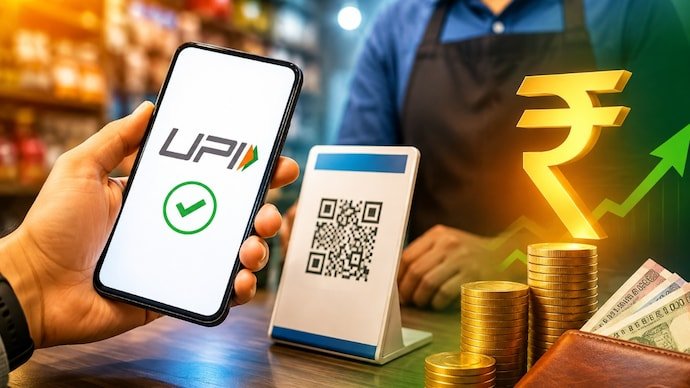
UPI has become deeply integrated into India’s digital payments system. From small neighbourhood stores to large retailers, QR-code payments have become a common way of completing transactions.
The introduction of MDR for specified high-value merchant payments therefore has implications beyond payment companies and banks. Retailers, businesses and payment service providers are also watching how the new framework works in practice.
The Supreme Court proceedings are particularly significant because the petition questions the legal and policy basis of the new arrangement. The petition has named the Union government, RBI, NPCI and other bodies as respondents. The court has sought their response while declining immediate interim relief.
For ordinary UPI users, the immediate position is relatively straightforward. A person sending money to another individual through UPI does not face the new MDR merely because the amount is above ₹2,000. Similarly, merchant transactions within the specified ₹2,000 threshold remain outside the new MDR framework. The distinction between personal transfers and merchant payments is therefore important when discussing the latest UPI charges in India.
What happens next?
The next stage will depend on the responses filed before the Supreme Court and further hearings in the case. Until the court changes the position or the authorities modify the framework, the current rules remain relevant for specified high-value merchant transactions.
The development also highlights the changing nature of India’s digital payments ecosystem. UPI was initially built around widespread, low-cost digital transactions, while the new MDR framework introduces a different structure for certain high-value merchant payments.
For consumers, the key point is that the Supreme Court has not ordered a blanket suspension of the new framework. The legal challenge remains pending, and the court’s further proceedings will determine how the issue develops.
As UPI continues to handle a large volume of digital transactions across India, the debate around payment costs, merchant sustainability and consumer convenience is likely to remain an important financial story in the coming weeks.